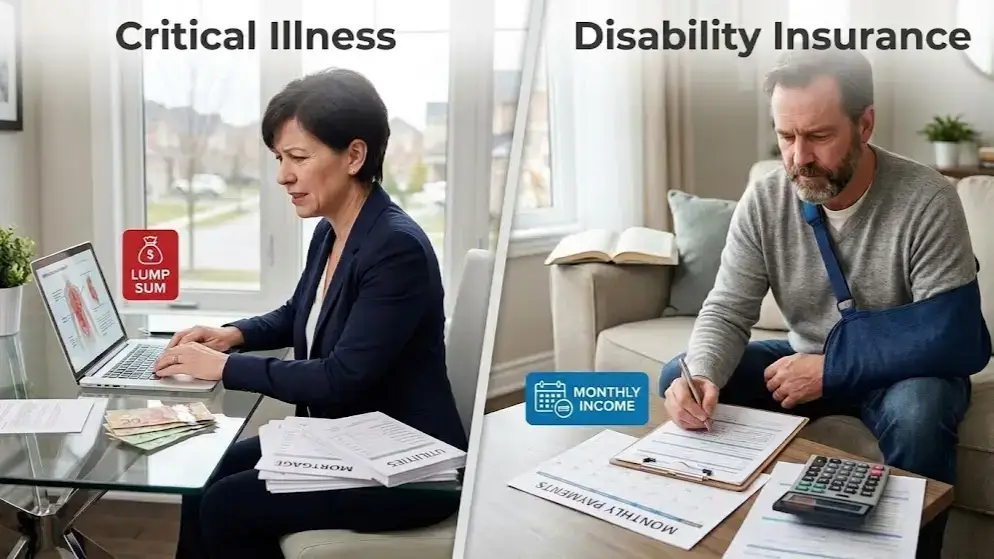
A sudden medical event or severe injury can disrupt your life without warning. Medical emergencies bring both physical strain and substantial financial challenges. While many Canadians believe standard health coverage solves every issue, government plans leave noticeable gaps in income protection and specialized recovery costs.
Living benefits provide crucial protection for these unexpected life situations. Two primary tools exist to protect your family and lifestyle: critical illness insurance and disability insurance. While both safeguard your financial health, they operate in distinct ways.
Understanding these differences helps you build a solid financial safety net.
Key Definitions: How Both Coverage Options Work
To choose the right protection, you must understand how each policy pays out and what triggers a benefit.
What is Critical Illness Insurance?
Critical illness insurance provides a lump-sum cash payout if you receive a diagnosis for a specific illness listed in your policy.
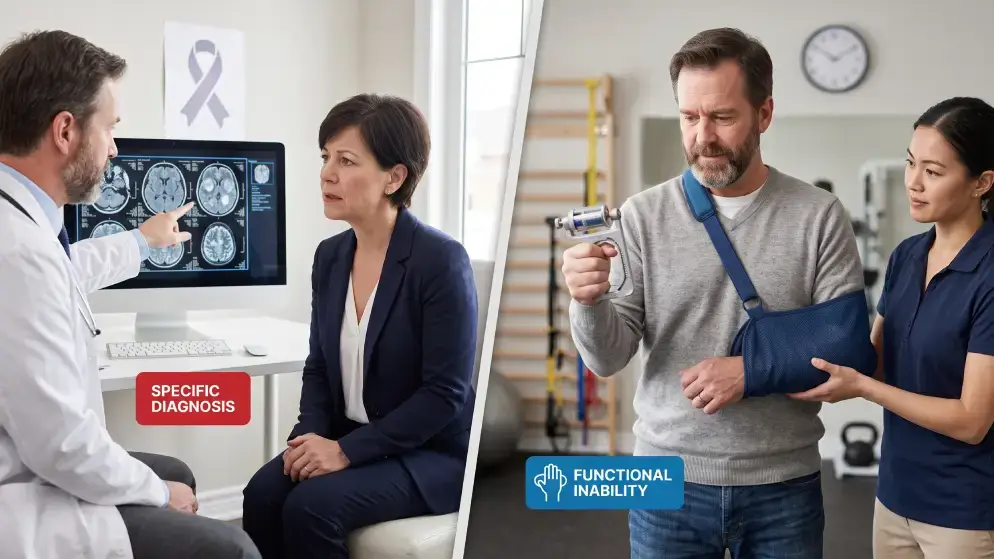
Trigger: Diagnosis of a covered medical condition, such as cancer, stroke, or heart attack.
Payout Method: Single, tax-free lump-sum payment.
Usage: You choose how to spend the funds. You can pay for out-of-province medical treatments, purchase medical equipment, reduce mortgage debt, or cover day-to-day bills while taking time off.
Work Status Requirement: You do not need to prove an inability to work; receiving a covered diagnosis is the primary requirement.
What Is Disability Insurance?
Disability insurance works as an income replacement plan if an injury or illness prevents you from performing your regular job duties.
Trigger: Inability to work due to a physical injury, accident, or chronic medical condition.
Payout Method: Regular monthly benefit payments, replacing a percentage of your regular income (typically 60% to 85%).
Usage: Designed to replace your regular paycheck so you can keep paying recurring fixed expenses like utilities, food, and housing costs.
Work Status Requirement: You must remain medically disabled and unable to work according to your policy definition to continue receiving benefits.
Primary Differences Between Critical Illness and Disability Insurance
Comparing these two options side-by-side highlights how they complement each other to form complete financial protection.
| Feature | Critical Illness Insurance | Disability Insurance |
| Payment Structure | Single lump-sum benefit | Monthly recurring payments |
| Primary Purpose | Covers major unexpected costs & medical expenses | Replaces regular earned monthly income |
| Eligibility Basis | Specific covered diagnosis | Inability to work due to injury or illness |
| Work Requirement | Payable even if you keep working | Requires proof of total or partial disability |
| Policy Duration | Ends after full payout is issued | Pays until you recover or reach maximum benefit period |
Choosing the Best Coverage for Your Life Stage
Determining which protection you need depends on your financial responsibilities, employment type, and existing safety nets.
When to Prioritize Disability Insurance
Disability insurance is vital if your family relies on your weekly or monthly earnings to cover regular household expenses. It is especially critical for:
– Self-employed professionals and business owners who lack corporate benefits packages.
– Primary household earners whose ongoing salary pays for rent, mortgages, and daily groceries.
– Tradespeople and physically demanding workers facing higher risk of workplace injuries.
When to Prioritize Critical Illness Insurance
Critical illness insurance provides financial relief when faced with expensive medical treatments, specialist care, or sudden lifestyle adjustments. Consider this coverage if:
– You have a family medical history with heart conditions, cancer, or strokes.
– You want funds available for private medical care, cutting-edge medications, or overseas clinical procedures.
– You need financial room so a family member can take time off work without pay to assist with your recovery.
Combining both policies ensures total security. Disability insurance replaces your monthly paycheck while critical illness insurance covers sudden, large lump-sum expenses.
Secure Your Financial Future Today
Unexpected health issues shouldn’t ruin your financial foundation. Navigating insurance options allows you to make confident decisions for your family’s future.
At AiA Insurance Brokers Ltd, our experienced insurance advisors tailor coverage options to your specific lifestyle and budget. Contact our team in Vaughan today to request a quote or review your current policy.
Official Source References and Links
Financial Consumer Agency of Canada’s guide on disability insurance
Ontario Disability Support Program (ODSP) benefits
FCAC guide to critical illness insurance
Financial Services Regulatory Authority of Ontario (FSRA) – to consult licensed Ontario insurance advisors